
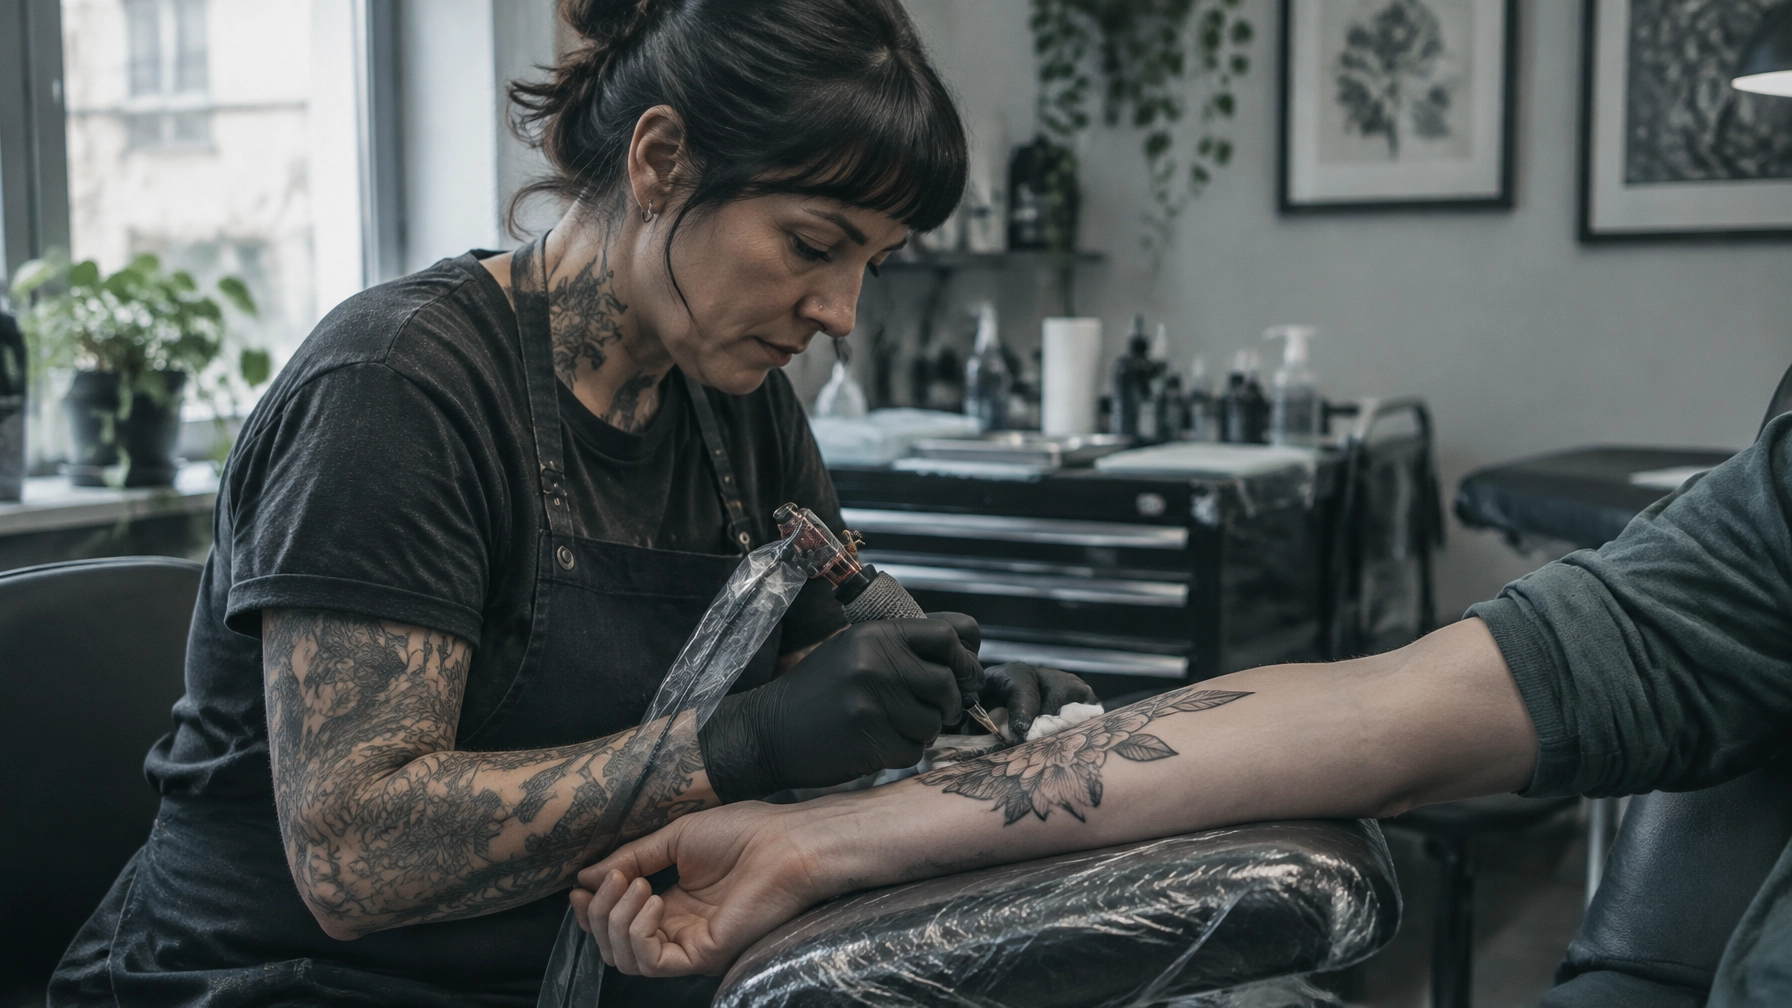
If you tattoo, pierce, rent a booth, or run a one-person studio in Indiana, Kansas, Missouri, or Delaware, an unexpected hospital stay can interrupt more than your workday. With no paid sick leave, income can stop while rent, booth fees, groceries, and studio expenses keep coming.
Hospital indemnity plans may help with that cash-flow pressure. They’re designed to pay a set cash benefit when a covered hospital event occurs, not to replace health insurance or cover the entire hospital bill. Here’s how to think about one as part of your coverage strategy.
Michael Peck is a licensed insurance agent, not a legal or financial advisor. This article is educational and does not replace personalized advice.
Why a hospital stay can hit a small tattoo business hard
Tattooing takes sustained concentration and repetitive work. Your hands and wrists stay active, your back may remain in one position for long stretches, and your eyes need to stay focused. An unexpected hospitalization can leave you unable to take appointments while you recover.
For a booth renter, that might mean lost bookings and booth rent that still comes due. If you own the studio, you may also have fixed costs, staff or contractor schedules to manage, and customers who need updates. Walk-ins may have to be turned away, and deposits or appointments may need to be rescheduled according to your studio’s policies.

What hospital indemnity plans can do
A hospital indemnity policy generally pays a fixed cash benefit when you meet the policy’s requirements for a covered hospital admission or stay. Depending on the plan, it may pay an admission benefit, a daily benefit for covered inpatient days, or both. The specific benefit amounts, covered events, limits, and exclusions depend on the policy.
The payment is typically made to you, rather than reimbursing the hospital for your actual bill. If a covered event qualifies, you can use the money for expenses such as rent, booth rent, groceries, utilities, transportation, or bills. Benefits are generally paid regardless of what other health insurance pays, subject to the policy terms.
That flexibility can matter when your schedule has no paid-leave cushion. But hospital indemnity coverage does not pay for every hospital visit, does not guarantee you’ll receive a benefit for every type of stay, and does not replace comprehensive health coverage.
What hospital indemnity does not replace
Hospital indemnity is supplemental coverage, not major medical insurance. It does not function like an ACA plan that can cover a broad range of essential health services, and its fixed benefits may be far less than the cost of your care. Read the schedule of benefits and policy details carefully so you know which events qualify, how benefits are triggered, and whether limits apply.
It also isn’t the same as disability-income coverage. A fixed hospital benefit may help with expenses after a covered stay, but it generally isn’t designed to replace all lost earnings if you can’t tattoo for an extended period without being hospitalized.
Build your coverage around the job and your budget
Start by considering your main medical coverage, then look at supplemental protection for specific financial gaps. The right combination depends on your health needs, income, budget, and eligibility.
- ACA: An ACA plan can provide comprehensive medical coverage, including protection for pre-existing conditions. Depending on your income and household details, you may qualify for premium tax credits that lower what you pay each month. Review ACA health plan options and understand how tax credits work for self-employed people.
- Short Term Medical: This may be an option for some people seeking temporary coverage, but it is not major medical and does not provide the same protections as an ACA plan. Compare its limits and exclusions before considering it.
- Accident: Accident coverage may provide set benefits for certain covered accidental injuries. It can be a separate gap-filler, but it is not designed to cover every illness or hospital event.
- Hospital indemnity: This may add a fixed cash benefit for qualifying hospital events, helping you manage everyday expenses while you’re unable to work.
- Critical care: Critical illness coverage may provide a benefit after a qualifying diagnosis, according to the policy’s definitions and requirements. It addresses a different kind of financial risk than hospital indemnity.
If you’re evaluating ACA coverage, consider your estimated annual income and how it may affect premium tax-credit eligibility. The “subsidy cliff” refers to the possibility that crossing an applicable income threshold can sharply change or eliminate tax-credit eligibility. The threshold and outcome depend on current rules and your household circumstances, so don’t rely on a rule of thumb; consider speaking with a tax professional.

Call Rachel at 512-850-6604 if you’d like help sorting through how supplemental coverage could fit alongside your main medical plan.
Check the details before you enroll
When comparing hospital indemnity plans, don’t focus only on the benefit headline. Look at the policy’s definitions and schedule, and ask:
- What counts as a covered hospital admission or inpatient day?
- Is there an admission benefit, a daily benefit, or both?
- Are there waiting periods, exclusions, or limits on the number of covered days?
- Does the policy require a particular type of facility or stay?
- When do coverage and benefits begin, and what information is needed to submit a claim?
A fixed cash benefit can offer flexibility, but only if you understand when it pays and how much. If you’re already covered by other insurance, ask how the hospital indemnity benefit works alongside it. It’s generally paid separately from your medical plan, but the policy terms control.
Plan enrollment around your coverage needs
For 2027 ACA coverage, Open Enrollment runs November 1, 2026, through January 15, 2027. If you want coverage to start January 1, 2027, the deadline to enroll is December 15, 2026. Outside Open Enrollment, you may qualify to enroll after a qualifying life event. Learn more about Open Enrollment and Special Enrollment.
Hospital indemnity enrollment and availability can follow different rules from ACA enrollment, so check the specific product’s timing and eligibility. If you’re balancing studio cash flow, health coverage, and tax-credit questions, it can help to review your options before you need to make a rushed decision.
Licensed agents and Marketplace Navigators: different kinds of help
Government-funded Marketplace Navigators and CMS assisters can help you understand enrollment steps and complete paperwork. They generally do not recommend a specific plan or act as your insurance agent.
A licensed health or life insurance agent can discuss plan features, help you compare options, and provide recommendations based on the information you share. Michael Peck is a licensed independent agent, and our goal is to offer year-round support from a real person who knows your name, not leave you to decipher plan details alone.
Call Rachel at 512-850-6604 to talk through your questions with someone who can help you compare options.
A practical next step for your studio
Write down what you’d still need to pay if a hospital stay kept you away from the studio: housing, booth rent, utilities, groceries, and business costs. Then compare that pressure point with the benefits and limits of any hospital indemnity policy you’re considering. This won’t tell you which plan to buy, but it gives you a clearer way to judge whether a fixed benefit could help.
You can also start by reviewing your core medical coverage, your estimated income, and any supplemental policies you already have. If you want a second set of eyes, ask questions before enrolling and make sure you understand what each policy does, and what it doesn’t do.
Call Rachel at 512-850-6604 if you’d like a real person to help you think through your coverage choices.
If you’re ready to compare options for your situation in Indiana, Kansas, Missouri, or Delaware, start a quote online, or reach out to our team. We’ll help you review the choices and understand how they may fit your budget and work life.
Or call us directly at 512-850-6604.
There are always options to explore. All you need to do is schedule an appointment with me and we will look at what is available for your situation.
Rachel at 512-850-6604
Michael Peck is a licensed insurance agent, not a legal or financial advisor. Real Health Quote is an independent health insurance agency licensed in 15 states (TX, DE, FL, IN, KS, MS, MO, NC, SC, OH, OK, MI, TN, GA, VA). Products and availability vary by state. We are not affiliated with or endorsed by any government agency, the federal Marketplace, or Medicare. Health insurance regulations and plan details can change; always consult with a professional regarding your specific tax or legal situation.

Leave a Reply