
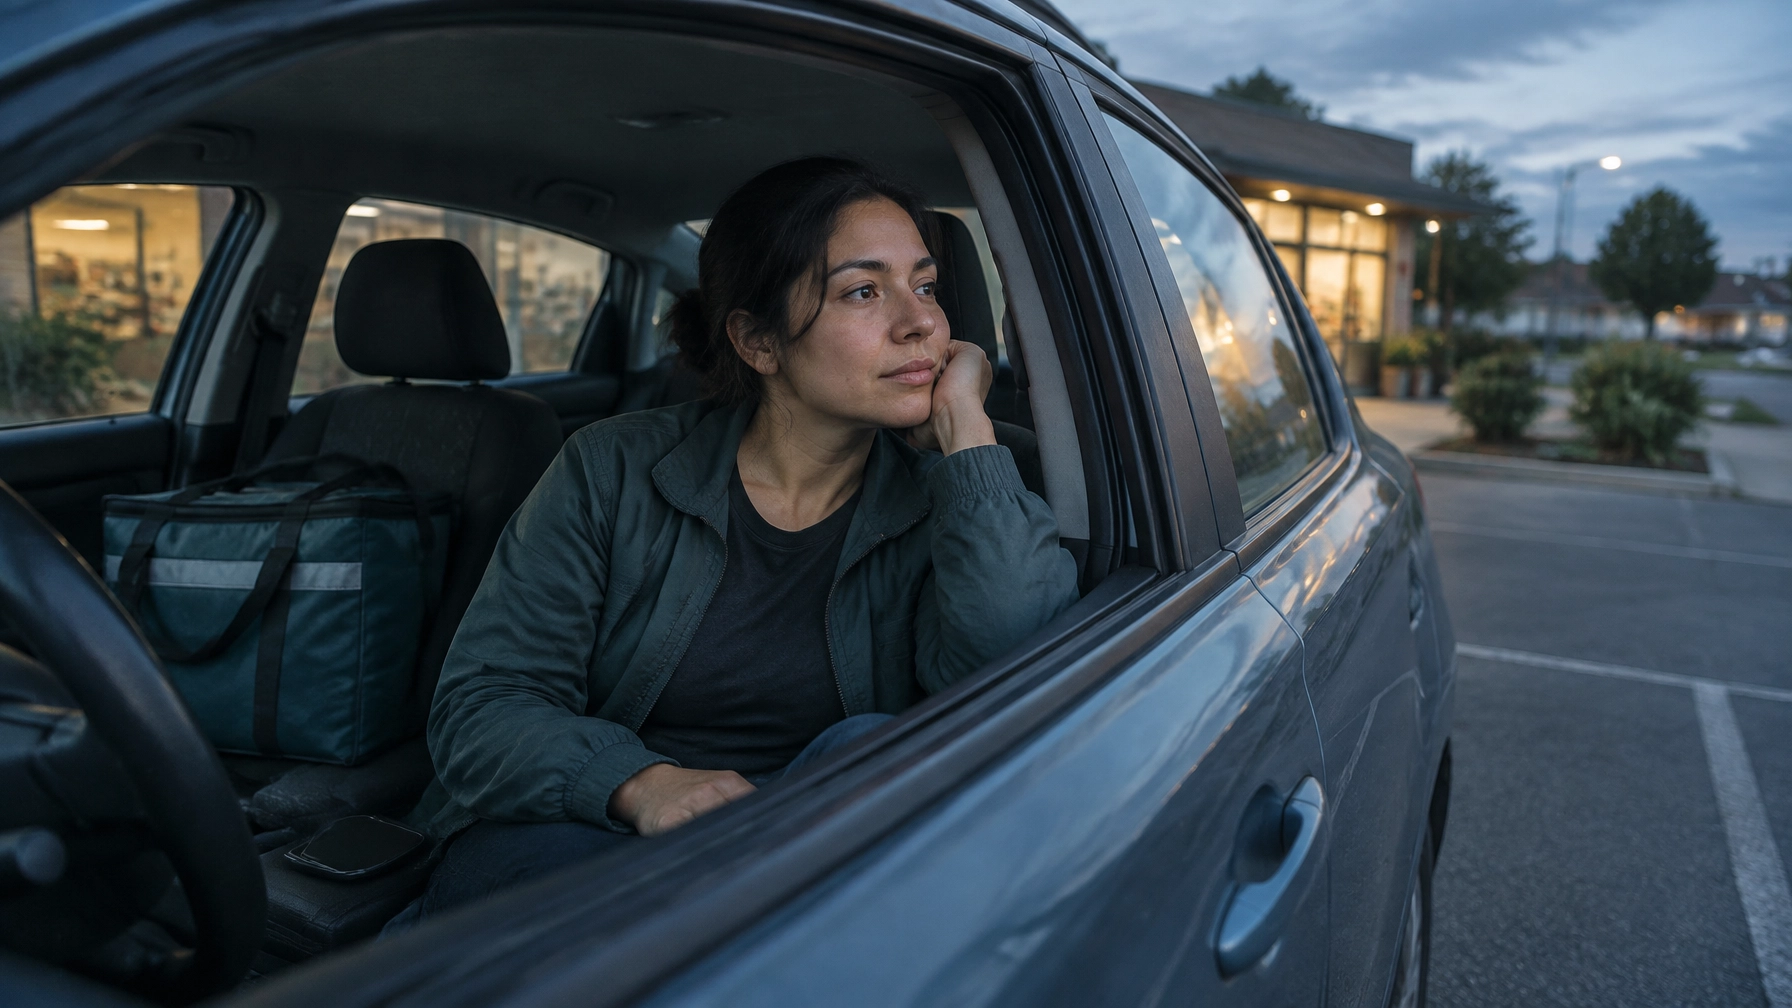
You finished a long shift, parked the car, and finally have a quiet moment, but health coverage is still sitting on your mental to-do list. Whether you drive for a rideshare app in Texas, deliver packages in Florida, freelance from Delaware, or work 1099 contracts in Indiana, choosing health insurance without an employer benefits department can feel like another full-time job.
The good news is that you have options. This evening guide breaks down health insurance for gig workers, including ACA plans, Short Term Medical, and supplemental gap fillers, so you can make a practical decision based on your income, health needs, and work situation.
Start With Your Real Work Situation
Gig work is flexible, but your income may change from week to week. You might combine delivery driving with freelance work, seasonal contracts, rideshare driving, or a small business. That makes choosing a health plan different from simply selecting the cheapest monthly premium.
Before comparing health plans, gather:
- Your best estimate of annual household income
- Your expected tax filing status and household size
- Your doctors, prescriptions, and preferred hospitals
- Your county and state of residence
- Any recent loss of employer coverage
- Your preferred budget for premiums and out-of-pocket costs
If you live in Texas, Delaware, Florida, or Indiana, plan availability and provider networks can vary by county. A plan that looks attractive in one Florida county may not offer the same doctors or hospitals in another.
Call Rachel at 512-850-6604 if you want help organizing these details before you compare plans.
The Big Three Filters for Gig Worker Health Insurance
When you are comparing coverage, use The Big Three Filters. These three questions can quickly narrow down which product category may fit.
1. Tax History
ACA plans use your projected household income and tax information when determining eligibility for premium tax credits. If you qualify, premiums can be as low as $0 based on tax credits, depending on your household details and plan choices.
As a self-employed person, your income estimate may be more complicated than a regular paycheck. You may need to account for business expenses, seasonal income, multiple sources of work, and changes in your schedule. If your income changes significantly during the year, update your application so your financial assistance is as accurate as possible.
Self-employed individuals may also qualify for a health insurance premium deduction, but tax treatment depends on your circumstances. Ask your tax professional how your coverage fits into your tax return.
2. Pre-existing Conditions
ACA plans cover pre-existing conditions. Your medical history cannot be used to deny you coverage or charge you more because of a health condition.
This can make ACA coverage especially important if you take regular prescriptions, manage diabetes, need ongoing treatment, or want predictable protection for a family member. Short Term Medical plans work differently and may exclude pre-existing conditions, so never compare them with ACA coverage as if they provide identical protection.
3. The Subsidy Cliff
The Subsidy Cliff affects ACA shoppers whose household income is above 400% of the Federal Poverty Level. With the expiration of enhanced subsidies, the original ACA rules and their limitations have returned.
For 2026, that can mean someone earning over roughly $64,000 as an individual or $132,000 for a family receives $0 in ACA tax credits, depending on household size and final eligibility calculations. If you are a middle-to-high income gig worker, the full-price ACA premium may not fit your budget.
That is where comparing other options may make sense. Short Term Medical can be a significantly more affordable PPO alternative for some healthy applicants facing the Subsidy Cliff, but it is not major medical and does not provide the same protections as an ACA plan.

Your Main Coverage Options
1. ACA
ACA coverage is often the first place to start for gig workers because it includes essential health benefits and protection for pre-existing conditions. It may also provide premium tax credits if your projected income falls within the eligibility range.
You can generally enroll during the annual Open Enrollment period, which runs from November 1 through January 15. A qualifying event, such as losing employer coverage, getting married, having a baby, or moving, may create a Special Enrollment Period outside those dates.
When comparing ACA plans, look beyond the premium. Check the deductible, copays, out-of-pocket maximum, prescription coverage, and whether your doctors participate in the plan’s network.
2. Short Term Medical
Short Term Medical can serve as a flexible bridge when you are between jobs, waiting for other coverage to begin, or earning too much for ACA tax credits. Some plans may offer nationwide PPO access, which can appeal to delivery drivers, traveling contractors, and other professionals who work across multiple locations.
However, STM is not major medical. It may limit or exclude pre-existing conditions, prescription benefits, maternity care, preventive services, or other categories covered more broadly by ACA plans. Review the exclusions, benefit maximums, renewal rules, and eligibility requirements carefully.
3. Accident
Accident coverage can help with certain unexpected injuries, such as those from a vehicle accident, fall, or workplace incident. It may pay a set cash benefit directly to you after a covered event.
For rideshare and delivery workers who spend many hours on the road, accident coverage may act as a useful gap filler. It does not replace comprehensive health insurance, but it may help with deductibles, transportation, groceries, or other bills after an accident.
4. Hospital
Hospital indemnity coverage may pay a fixed benefit when you experience a covered hospital stay or procedure. The money can help with expenses your primary health plan does not fully cover.
This type of coverage can be particularly useful if you have a high-deductible plan and want additional financial support for a serious medical event. Review the covered services and benefit amounts before enrolling.
5. Critical Care
Critical care coverage, often called critical illness coverage, may provide a cash benefit after the diagnosis of a covered serious condition. You can generally use the money for medical bills or household expenses.
For a self-employed worker, the benefit may help protect income while you recover and cannot drive, accept projects, or complete client work. Covered conditions and definitions vary, so read the policy carefully.
6. Term Life Insurance
Term life insurance provides protection for a specific period. It can help replace income or support your family if you die during the policy term.
If your household depends on your gig income, consider how rent, vehicle payments, childcare, and other financial obligations would be handled without you. Health coverage protects your access to care; term life insurance can help protect the people who depend on your income.
7. Dental
Dental coverage can help reduce the cost of exams, cleanings, fillings, and other eligible services. Dental benefits are usually separate from your medical plan.
If you are self-employed, routine dental care may be easy to postpone during a busy season. A dedicated dental plan can make it easier to budget for preventive care.
8. Vision
Vision coverage may help with eye exams, glasses, and contact lenses. If you drive at night, work on a computer, or rely on sharp vision for your job, regular eye care is worth considering.
These supplemental products are gap fillers. They should complement, not replace, the main medical coverage that fits your situation.
Licensed Agent vs. Navigator: Who Can Actually Advise You?
A Healthcare.gov Navigator/CMS Support staff member is a government-funded facilitator. Navigators can help explain application procedures, assist with paperwork, and direct you through the enrollment process. They are legally barred from giving advice or recommending a specific plan.
A licensed health or life insurance agent, such as Michael Peck, can provide advice based on your budget, doctors, prescriptions, expected income, and coverage priorities. An independent agent can compare available products, explain differences between ACA and Short Term Medical, recommend plans that may fit your needs, and provide year-round support after enrollment.
That distinction matters when you are weighing network access, deductibles, tax credits, pre-existing conditions, or the Subsidy Cliff. You deserve to understand not just how to enroll, but what you are actually buying.
A Simple Evening Checklist
You do not need to solve everything after one shift. Set aside 20 to 30 minutes and take these steps:
- Write down your estimated household income for the year.
- Note your state and county, whether Texas, Delaware, Florida, or Indiana.
- List your doctors, prescriptions, and preferred hospitals.
- Decide whether you need comprehensive ACA coverage or are evaluating a temporary option.
- Review the deductible and out-of-pocket maximum, not just the premium.
- Ask whether supplemental coverage could help with accident, hospital, or critical-care costs.
- Put a reminder on your calendar for Open Enrollment or any qualifying-event deadline.
Call Rachel at 512-850-6604 when you want a real person to walk through the checklist with you.

Build a Strategy That Fits Your Income
There is no single best gig worker health insurance plan for everyone. A young delivery driver with no ongoing prescriptions may prioritize a different network and deductible than a 1099 contractor supporting a family.
If you are searching for self-employed health insurance in Texas, comparing ACA Marketplace options in Florida, or reviewing health plans in Delaware or Indiana, the right answer depends on your complete picture. It may be an ACA plan with tax credits, an unsubsidized option, Short Term Medical, or a combination of medical and supplemental coverage.
You can also read Real Health Quote’s 2026 guide to health insurance for gig workers, simple ACA guide for self-employed people, and breakdown of ACA tax credits before your conversation.
Call Rachel at 512-850-6604 and take the guesswork out of your next step. You can also request a quote from Real Health Quote to compare coverage based on your actual situation.
When you are ready to turn tonight’s planning into action, request your personalized health insurance quote here.
Or call us directly at 512-850-6604
There are always ways to find you coverage, all you need to do is schedule an appointment with me and I will find you something.
Rachel – 512-850-6604
Michael Peck is a licensed insurance agent, not a legal or financial advisor. Real Health Quote is an independent health insurance agency licensed in 15 states (TX, DE, FL, IN, KS, MS, MO, NC, SC, OH, OK, MI, TN, GA, VA). Products and availability vary by state. We are not affiliated with or endorsed by any government agency, the federal Marketplace, or Medicare. Health insurance regulations and plan details can change; always consult with a professional regarding your specific tax or legal situation.

Leave a Reply