
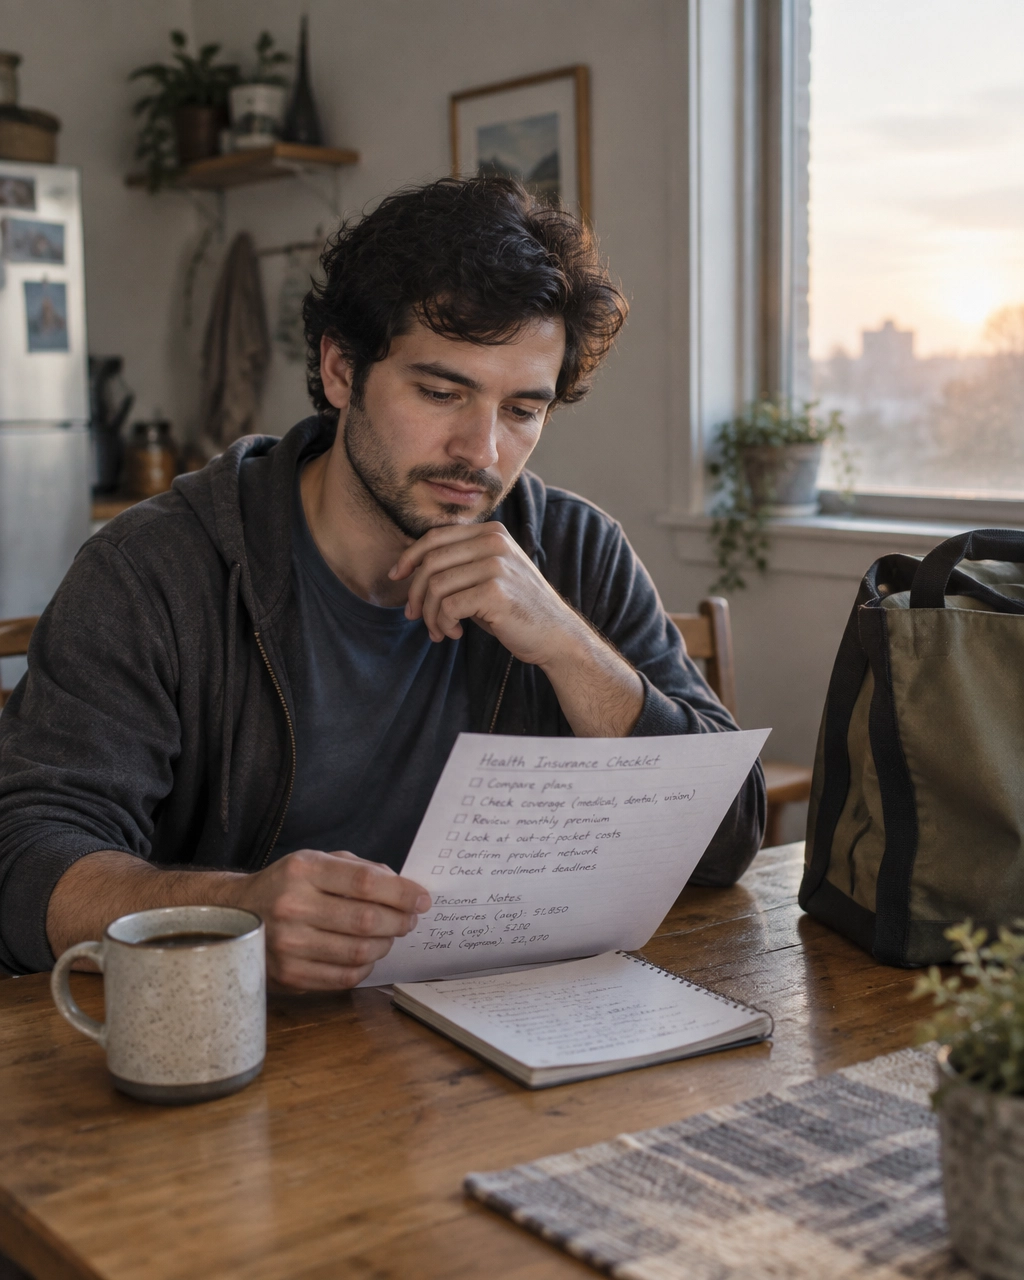
Before your first delivery, rideshare pickup, freelance client, or route of the day, you may already be juggling income estimates, mileage records, prescriptions, and the worry of an unexpected medical bill. When you work for yourself, health insurance is another responsibility on a very full list.
The good news is that you can make the decision easier with a simple morning strategy. This guide breaks down gig worker health insurance options in Delaware, Indiana, Mississippi, and Missouri, including ACA marketplace plans, Short Term Medical, and supplemental gap fillers.
Your 10-Minute Morning Insurance Routine
You do not need to spend an entire weekend sorting through insurance details. Start with these four steps and write down the answers in one place.
Minute 1–3: Estimate your household income
Use your best current estimate of your yearly household income, not just what you earned last week. For gig workers, that may include delivery income, rideshare earnings, freelance payments, contract work, and other taxable income.
Because your income can change throughout the year, update your estimate when your work schedule, clients, or household situation changes. Your income estimate can affect ACA tax credits and Medicaid eligibility.
Minute 4–5: List your doctors and prescriptions
Write down the doctors you want to keep, the hospitals you prefer, and every prescription you take. A plan that looks affordable may not be a good fit if your doctor is outside the network or your medication is not covered favorably.
You should also check whether the plan uses an HMO, EPO, or PPO network and whether referrals are required for specialists.
Minute 6–7: Identify your enrollment window
Ask whether you are in an annual enrollment period or qualify for a Special Enrollment Period because of a life event, such as losing job-based coverage, moving, getting married, or having a child. If you recently lost coverage, do not wait until you need care to confirm your options.
Minute 8–10: Compare total costs
Do not compare premiums alone. Review the deductible, copays, coinsurance, prescription costs, provider network, out-of-pocket maximum, and what you could realistically pay during a difficult medical year.
This ten-minute habit gives you a clearer starting point before you compare plans. Call Rachel at 512-850-6604 for a quick morning insurance reset.

The Big Three Filters for Gig Worker Health Insurance
When you compare ACA marketplace coverage, Short Term Medical, or supplemental products, use these three filters first.
1. Tax History
ACA plans use your expected household income for the coverage year when determining eligibility for premium tax credits. Your final tax return can later be used to reconcile the amount of assistance you received.
That means your income estimate matters. If your gig income rises significantly, update your application information so you can reduce the risk of an unexpected tax issue later. If your income falls, updating your estimate may help you qualify for more assistance if you are otherwise eligible.
This is especially important for 1099 workers because gross deposits are not always the same as taxable household income. Keep organized records and discuss tax questions with a qualified tax professional.
2. Pre-existing Conditions
ACA coverage must cover pre-existing conditions. You generally cannot be denied or charged more because you have diabetes, asthma, a prior surgery, high blood pressure, or another medical history concern.
Short Term Medical works differently. It is not major medical, and it may exclude pre-existing conditions, deny an application based on health history, or limit coverage for conditions that existed before the policy began.
3. The Subsidy Cliff
The enhanced ACA subsidies expired, so the original ACA rules are back for 2026. Under those rules, the federal premium tax credit generally ends when household income goes above 400% of the federal poverty level.
For planning purposes, that is approximately $64,000 for one person or $132,000 for a family, although the exact amount depends on household size and the applicable federal guidelines. If you earn even slightly over the limit, you could receive $0 in federal tax credits. That sharp cutoff is known as the Subsidy Cliff.
The original ACA income cap and subsidy structure are back in effect for 2026.
State Notes for Delaware, Indiana, Mississippi, and Missouri
Your state, household size, age, and income all affect which coverage options are available. Gig income fluctuates, so review your estimate whenever your work pattern changes.
- Delaware: Delaware is a small state, and you should not assume that every low-income adult will qualify for Medicaid. Review the state’s current eligibility categories and compare them with ACA options before choosing coverage.
- Indiana: Indiana does not have broad Medicaid expansion for every low-income adult. Some people may qualify through specific eligibility categories, but your household details and income estimate matter.
- Mississippi: Mississippi has not expanded Medicaid for all low-income adults. Childless adults may have limited pathways to Medicaid, making accurate income estimates and private coverage comparisons particularly important.
- Missouri: Missouri expanded Medicaid eligibility for many adults, so some gig workers with lower household income may qualify through the state’s adult coverage program. You still need to report income accurately and watch for renewal notices.
A licensed agent can help you compare your coverage options based on your doctors, prescriptions, and budget.
Call Rachel at 512-850-6604 when fluctuating gig income makes your state options hard to sort out.
When Short Term Medical May Be Worth Comparing
For middle-to-high income earners above the Subsidy Cliff, an ACA plan without tax credits may not fit the budget. In that situation, Short Term Medical may be a more affordable PPO alternative for some people, particularly those who are generally healthy and need temporary protection.
Some Short Term Medical plans offer access to broad or nationwide PPO networks. That can be useful if you drive across state lines, travel for work, or serve clients in multiple areas.
However, STM is not major medical. It may exclude pre-existing conditions, maternity care, mental health services, certain prescriptions, or other benefits you expect from comprehensive coverage. It may also have benefit limits, medical underwriting, or policy-term restrictions.
Before choosing STM, ask:
- Is my current health history excluded?
- Are my doctors and hospitals in the PPO network?
- What services are limited or excluded?
- What is the maximum policy duration in my state?
- Does the plan cover the type of care I am most likely to need?
A lower premium does not automatically make a plan the right plan. The goal is to understand the tradeoffs before you enroll.
Your Product Checklist, in the Right Order
A licensed agent can help you compare coverage categories instead of assuming one product solves every problem.
- ACA: Comprehensive coverage that includes essential benefits and protection for pre-existing conditions. Premium tax credits may be available when you meet the income requirements.
- Short Term Medical: Temporary coverage that may offer PPO access but is not major medical and may exclude pre-existing conditions.
- Accident: A gap filler that may provide cash benefits after covered accidental injuries.
- Hospital: Supplemental coverage that may help with certain hospital stays or admissions.
- Critical illness: A cash-benefit product that may help with expenses after a covered serious diagnosis.
- Term life insurance: Financial protection for people who depend on your income.
- Dental: Separate coverage for cleanings, exams, fillings, and other eligible dental services.
- Vision: Help with exams, glasses, or contacts, depending on the plan.
These products are not interchangeable. An accident plan does not replace health insurance, and a hospital plan does not provide the same protection as comprehensive medical coverage. Think of supplemental products as gap fillers that may support your main strategy.
For more details, review Real Health Quote’s ACA health plan overview.

Licensed Agents vs. Navigators and CMS Support Staff
Healthcare.gov Navigators and CMS Support staff are government-funded facilitators. They can help consumers understand application steps, complete paperwork, and navigate enrollment processes, but they are legally barred from giving personalized advice or recommending a specific plan.
A licensed health or life insurance agent can provide a different kind of support. A licensed agent such as Michael Peck can review your situation, recommend options, compare available plans, explain exclusions and networks, and help you revisit your coverage when your income or family situation changes.
Michael Peck is licensed in Delaware, Indiana, Mississippi, and Missouri. The value of working with an independent agent is having a dedicated advocate who can help you evaluate your choices rather than leaving you to interpret every plan detail alone.
Call Rachel at 512-850-6604 for friendly help connecting with the right licensed support.
Start Your Day With a Clearer Coverage Plan
You do not have to solve every insurance question before your first cup of coffee. Start by estimating your income, checking your doctors and prescriptions, identifying your enrollment window, and comparing the total cost of each option.
Then apply the Big Three Filters: Tax History, Pre-existing Conditions, and the Subsidy Cliff. Whether you are delivering packages in Delaware, driving passengers in Indiana, freelancing in Mississippi, or working contracts in Missouri, the right strategy should fit both your health needs and the way your income actually works.

When you are ready to compare your choices, request a personalized quote from Real Health Quote or call 512-850-6604. Our team can help you review ACA coverage, Short Term Medical, and supplemental gap fillers with your budget and situation in mind.
There are always ways to find you coverage, all you need to do is schedule an appointment with me and I will find you something.
Rachel – 512-850-6604
Michael Peck is a licensed insurance agent, not a legal or financial advisor. Real Health Quote is an independent health insurance agency licensed in 15 states (TX, DE, FL, IN, KS, MS, MO, NC, SC, OH, OK, MI, TN, GA, VA). Products and availability vary by state. We are not affiliated with or endorsed by any government agency, the federal Marketplace, or Medicare. Health insurance regulations and plan details can change; always consult with a professional regarding your specific tax or legal situation.

Leave a Reply