
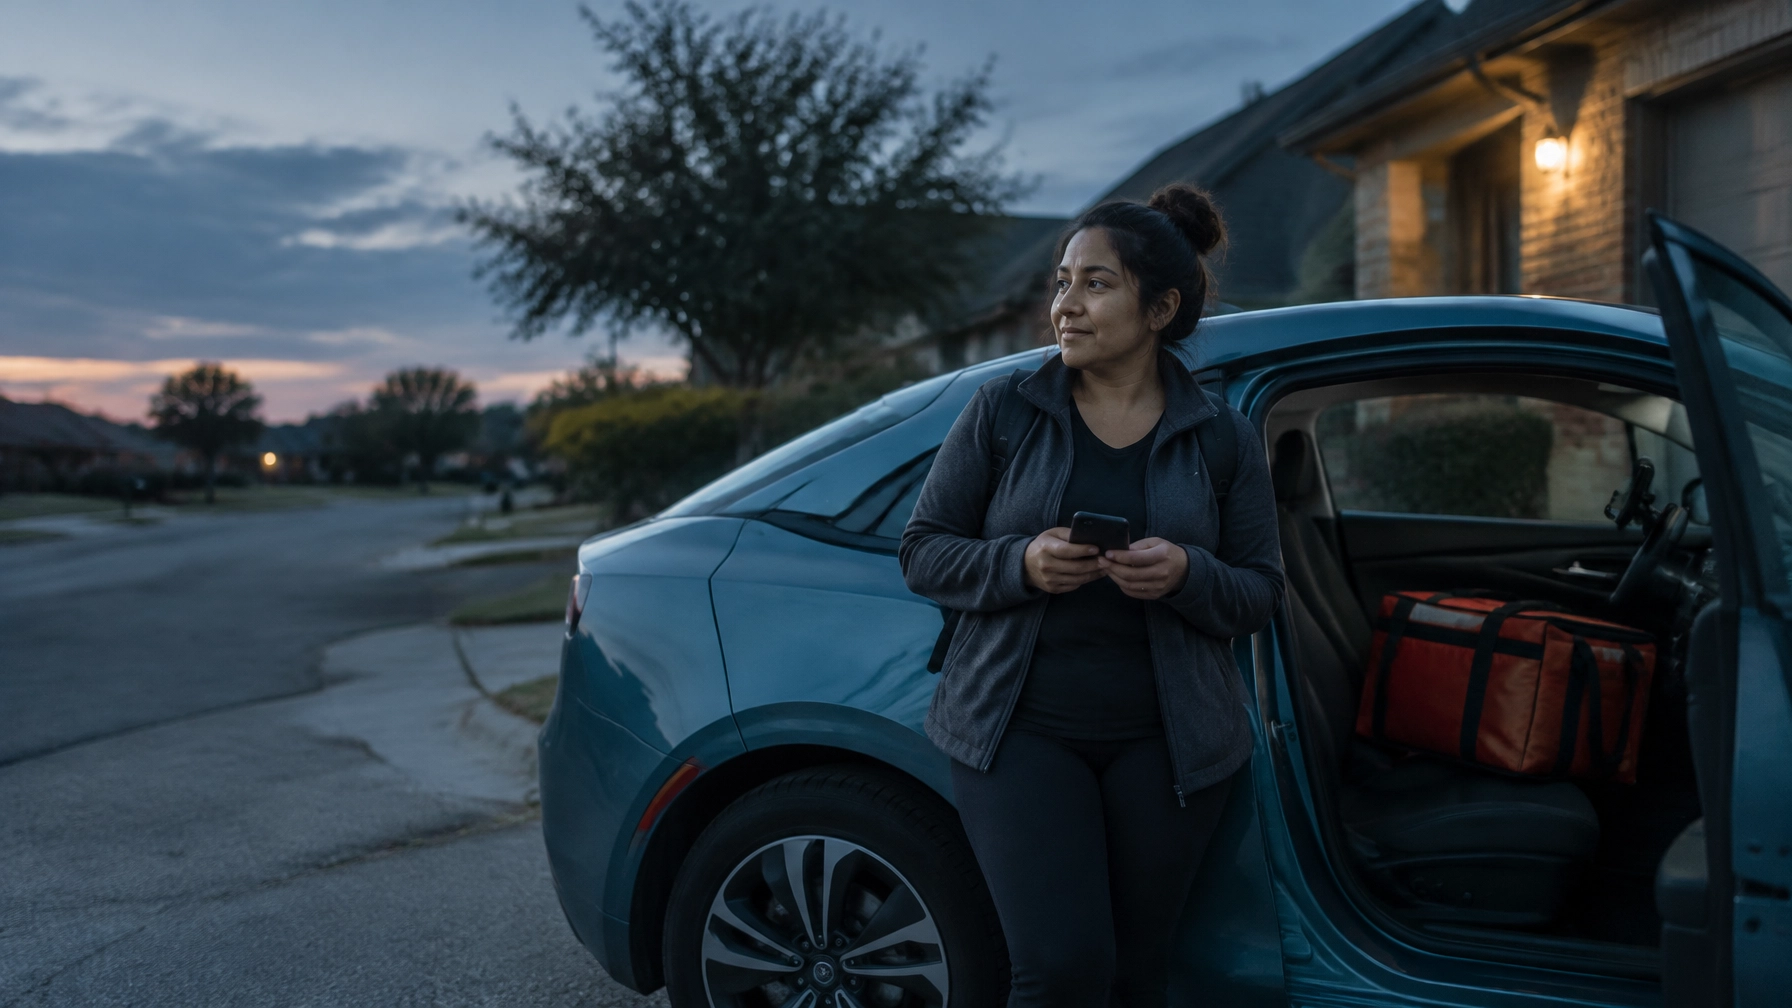
You finish your DoorDash, Uber Eats, Instacart, Grubhub, or Amazon Flex shift, park the car, and finally have a quiet moment to think about health insurance. Then the questions start: What will your 1099 income look like next year? Can you afford an ACA plan? What happens if your income crosses a tax-credit threshold?
If you drive nights and weekends in Texas, Florida, Georgia, or Ohio, this is the right time to make a plan. The 2027 Open Enrollment period runs from November 1, 2026, through January 15, 2027. If you want coverage to begin January 1, 2027, December 15, 2026, is the important enrollment target.
This after-the-shift guide breaks down your options and gives you a practical checklist for unpredictable gig income.
Start With Your Real 1099 Income Picture
Your delivery-app deposits are only part of the story. For health insurance planning, you should look at expected household income and your net self-employment income rather than treating every dollar of gross app revenue as available income.
Before November 1, gather:
- Year-to-date earnings from every delivery platform
- Your expected driving and delivery schedule for 2027
- Mileage and other legitimate business-expense records
- Income from a spouse, second job, freelance work, or other contracts
- Household size and expected changes
- Current doctors, prescriptions, and preferred hospitals
- Your target budget for premiums and out-of-pocket costs
Income can change quickly when you drive around holidays, pick up extra shifts, or reduce your hours. Use a realistic estimate based on your full household, not just your strongest month, and update your information when your situation changes.
In Texas, Florida, and Georgia, many delivery drivers are self-employed without access to employer benefits. Ohio drivers may also compare individual coverage if their app work is their primary income or they are between jobs.
Call Rachel at 512-850-6604 to get your enrollment checklist started.

Know the 2027 Enrollment Calendar
You do not have to enroll the moment Open Enrollment begins, but starting early gives you time to check networks, prescriptions, deductibles, and income details.
Here are the key dates:
- November 1, 2026: 2027 Open Enrollment begins
- December 15, 2026: Target deadline for a January 1, 2027, effective date
- January 15, 2027: Open Enrollment ends
- After December 15: Enrollment generally results in a February 1 effective date, subject to applicable rules and processing
If you currently have coverage, check its renewal information before choosing something new. If you are uninsured, do not assume you need to wait until November 1 to ask questions or organize your documents. You can prepare your income estimate, provider list, and coverage priorities now.
Use The Big Three Filters Before Comparing Plans
Gig worker health insurance becomes easier to understand when you apply the same three questions to every option.
1. Tax History
ACA tax credits are connected to household information, projected annual income, and tax filing requirements. You should keep prior tax information, current income records, mileage documentation, and your method for estimating 2027 income in one place.
If you receive advance tax credits, your final eligibility is reconciled through your tax return. That is why an honest income estimate matters. Underestimating income can create an unpleasant surprise later, especially if your delivery work becomes busier than expected.
2. Pre-existing Conditions
ACA plans cover pre-existing conditions. That protection matters if you take regular prescriptions, see a specialist, manage diabetes or high blood pressure, or expect ongoing medical care.
Short Term Medical is different. STM is medically underwritten, so your health history may affect eligibility, exclusions, benefits, or limitations. Read the policy language carefully before applying.
3. The Subsidy Cliff
With enhanced subsidies expired, the original ACA rules and their limitations have returned. The Subsidy Cliff is the point at which a household earning over 400% of the federal poverty level may receive $0 in tax credits for an ACA plan.
For general planning purposes, that is approximately $64,000 for an individual or $132,000 for a family. These are broad planning estimates only; household size, coverage year, and current rules affect the actual calculation.
This can be frustrating for a successful delivery driver or self-employed household. You may earn too much for tax credits while still finding full-price ACA premiums difficult to fit into your budget.
For some eligible middle-to-high income earners, STM may be a significantly more affordable PPO alternative when ACA coverage does not fit because of taxes or cost. STM is not Major Medical and does not provide the same protections as an ACA plan.
A PPO generally offers a broader provider network and more flexibility than a narrow-network plan, but the actual network and out-of-network rules vary by policy. STM can be more than a simple stopgap for some applicants and may include access to a high-quality nationwide PPO. It still may exclude pre-existing conditions, limit benefits, or use different claims rules.
Call Rachel at 512-850-6604 and make the tax-credit questions easier to sort through.
Compare Your Coverage Options in the Right Order
Once you understand your income and health needs, compare products in this order:
-
ACA: ACA plans can provide comprehensive coverage, pre-existing-condition protection, preventive services, prescriptions, emergency care, and other essential benefits. Review the provider network, drug formulary, deductible, copayments, coinsurance, and out-of-pocket maximum, not just the premium.
-
Short Term Medical: STM may be worth comparing when you need flexibility or when ACA coverage does not fit because of cost or the Subsidy Cliff. It is medically underwritten, may exclude pre-existing conditions, and is not Major Medical.
-
Accident: Accident coverage may provide a cash benefit after a covered accidental injury. For a driver, it may help with expenses connected to a qualifying accident, but it is not a replacement for medical insurance.
-
Hospital: Hospital coverage may provide a fixed benefit after a covered hospital stay or service. It can act as a gap filler when you are concerned about the financial impact of hospitalization.
-
Critical care: Critical care coverage may provide a benefit after a qualifying serious illness or medical event. It is designed to provide financial support during recovery.
-
Term life insurance: Term life insurance can protect family members who depend on your delivery income. It is separate from health insurance and should be considered as part of your broader protection plan.
-
Dental: Dental coverage may help with exams, cleanings, preventive services, and other eligible care. Check waiting periods, annual maximums, networks, and exclusions.
-
Vision: Vision coverage may help with eye exams, lenses, frames, or contacts, depending on the policy.
These products serve different purposes. Accident, Hospital, Critical care, Dental, and Vision coverage can help fill specific gaps, but they do not replace comprehensive health coverage.

Licensed Agent vs. Marketplace Navigators and CMS Support Staff
You may encounter different types of enrollment assistance, so it helps to understand the difference.
HealthCare.gov Navigators and CMS support staff are government-funded facilitators. They can help with application steps, paperwork, and general enrollment procedures, but they are legally barred from giving individualized insurance advice or recommending a specific plan.
A licensed health/life insurance agent, such as Michael Peck, can provide personalized plan recommendations based on your household, projected income, doctors, prescriptions, health history, budget, and priorities. A licensed agent can explain tradeoffs between plan types, review network details, compare supplemental products, and provide year-round support after enrollment.
Michael Peck is a licensed agent, not a legal or financial advisor. Real Health Quote is an independent agency, so the goal is to help you compare available choices rather than leave you to decode plan documents alone.
Real Health Quote can assist residents in Texas, Delaware, Florida, Indiana, Kansas, Mississippi, Missouri, North Carolina, South Carolina, Ohio, Oklahoma, Michigan, Tennessee, Georgia, and Virginia. Product availability and plan details vary by state.
Call Rachel at 512-850-6604 to compare your options with a real person.
Your After-the-Shift Checklist
Before November 1, set aside one evening to answer these questions:
- What is my best estimate of 2027 household income?
- Have I included every delivery app and other source of income?
- Have I recorded mileage and other legitimate business expenses?
- Could my household be near the Subsidy Cliff?
- Which doctors, hospitals, and prescriptions must my plan include?
- Do I need ACA protection for a pre-existing condition?
- Would the limitations of STM fit my health and financial situation?
- Is a January 1 effective date important to me?
- Would supplemental coverage help fill a specific financial gap?
- Do I understand the deductible and out-of-pocket maximum?
You do not need to solve your entire health insurance situation while sitting in your car between deliveries. Start with your records, identify your priorities, and compare the full cost and protection of each option.
When you are ready, request a personalized quote from Real Health Quote. You can also review our ACA health plan information as you prepare for 2027.
Real Health Quote can help you compare health insurance for gig workers, Short Term Medical, and supplemental products based on your state, household, income, health needs, and budget. Start your quote online or call 512-850-6604 to take the next step with a real person.
Or call us directly at 512-850-6604.
There are always ways to find you coverage—all you need to do is schedule an appointment with me and I will find you something.
Rachel – 512-850-6604
Michael Peck is a licensed insurance agent, not a legal or financial advisor. Real Health Quote is an independent health insurance agency licensed in 15 states (TX, DE, FL, IN, KS, MS, MO, NC, SC, OH, OK, MI, TN, GA, VA). Products and availability vary by state. We are not affiliated with or endorsed by any government agency, the federal Marketplace, or Medicare. Health insurance regulations and plan details can change; always consult with a professional regarding your specific tax or legal situation.

Leave a Reply